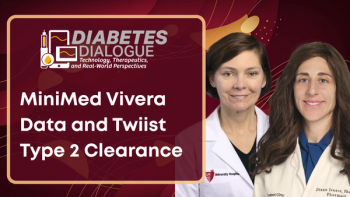
Diana Isaacs, PharmD, and Natalie Bellini, DNP, review early MiniMed Vivera data on optional meal announcements and twiist's new type 2 diabetes clearance.
Since 1997, several teaching hospitals haveengaged in a running skirmish with the IRS overthe tax status of resident physicians and whetherthe hospitals must make contributions for them underthe Federal Insurance Contribution Act(FICA). For the past several years, theseteaching hospitals have sought toexempt residents under the tax clause thatexempts student employees from FICAtaxes. In addition, the hospitals have askedfor refunds of more than $162 million inFICA taxes that have already been paid.
The IRS recently announced aproposed regulation that would clarify the studentemployment exemption and, in the process, removethe exemption for most residents. The agency alsoannounced that it would come up with a procedurewithin 90 days for resolving any outstandingappeals. The proposed regulation wouldapply the student exemption onlywhen education predominates overemployment in the relationship betweenresident and hospital. It would not applyif an employee is a professional, works morethan 40 hours a week, and is eligible to participatein a retirement benefits program.
about 18 years ago
Examine the Current Recruitment Trendsabout 18 years ago
Teach Your Kids Priceless Money Lessonsabout 18 years ago
Recognize a Suitable Employment Offerabout 18 years ago
Grasp the Shaky Economics of Medicineabout 18 years ago
Choose Between a Big Hat or Big Cattleabout 18 years ago
Safeguard Your Assets with Solid Trustsabout 18 years ago
Medicare Payments Under a Cloudabout 18 years ago
Doc Execs Rake It Inabout 18 years ago
Careful on Medicare Chargesabout 18 years ago
On-Call Physicians Pay